- Free Consultation* (316) 265-0797 Tap Here to Call Us


How Often Should You Update Your Estate Plan? A Practical Review Checklist


Estate planning is not a one-time task. A will, trust, power of attorney, health care directive, and beneficiary designation can be excellent documents when signed—and still become outdated as life, finances, relationships, and the law change.
For many people, a review every three to five years is a sensible baseline. You should also revisit your estate plan promptly after a major life event. The goal is not necessarily to rewrite every document; it is to confirm that the plan still reflects your wishes, the people you want to protect, and the assets you own.
The Short Answer: Review Your Estate Plan Every 3–5 Years
A periodic review can help identify changes before they create avoidable confusion, delay, expense, or conflict. During that review, consider your will or trust, financial power of attorney, health care documents, beneficiary designations, property titling, and any business succession planning.
A regular review is especially useful because estate plans often involve more than one document. Updating a will without checking retirement-account beneficiaries or transfer-on-death designations, for example, may leave important parts of the overall plan misaligned.
Life Events That Should Prompt an Estate-Plan Review
Some changes deserve attention sooner than the next scheduled review. Consider speaking with an estate-planning attorney after any of the following:
Marriage, divorce, or a new long-term relationship
Marriage may affect inheritance rights and the people you want to name as beneficiaries, fiduciaries, or health care decision-makers. Divorce can create an urgent need to review beneficiary designations and appointments under existing documents. A new long-term relationship may also change your priorities for housing, support, blended-family planning, and decision-making authority.
Birth, adoption, or changing needs of a child or grandchild
The arrival of a child or grandchild may affect who should inherit, who should serve as guardian, and how assets should be held or managed. If a beneficiary is disabled, struggles with creditors, or is not ready to manage an inheritance directly, a tailored planning discussion may be appropriate.
Death or incapacity of a named person
Review your plan if a beneficiary, executor, trustee, guardian, agent, or health care surrogate dies or can no longer serve. Every important appointment should have a practical successor.
A significant change in assets or debt
Buying or selling a home, receiving an inheritance, starting or selling a business, acquiring investment property, or experiencing a substantial change in wealth may alter how your plan should work. New assets should also be reviewed for title and beneficiary-designation issues.
A move to another state
Estate-planning documents may remain useful after a move, but state rules and execution requirements can vary. A review with counsel in the new state can help confirm whether the existing plan remains effective and complete. For example a move to Florida would probably necessitate updated documents as they have different rules regarding execution and other provisions related to various documents.
A change in tax, probate, trust, or beneficiary law
Changes in the law can affect planning strategies and administration. An attorney can help determine whether a legal development requires a document update or simply changes how the plan should be administered. For example with the changes to the Federal estate taxes in the past few years complex trust arrangements are no longer necessary for most individuals allowing many estate plans to be simplified.
Changes in family dynamics or your intended beneficiaries
Plans should reflect current relationships and intentions. If you want to add or remove a beneficiary, change a charitable gift, alter distributions, or adjust who receives family property, do not rely on informal promises or handwritten notes outside your signed documents. What your documents say or who you have designated as beneficiary are going to control and any oral statements or handwritten changes are likely not legal or effective.
What to Review in an Estate Plan
A thoughtful estate-plan review usually covers these items:
- Will and revocable trust: Do the dispositive provisions, fiduciary appointments, and successor provisions still match your wishes?
- Beneficiary designations: Are retirement accounts, life insurance, annuities, and payable-on-death accounts coordinated with the plan? Have you verified the current beneficiaries are who you want with the account holder?
- Powers of attorney: Is the financial agent trustworthy, available, and still the right person to act?
- Health care documents: Are your health care agent and treatment preferences current?
- Guardianship nominations: If you have minor children, are the nominated guardians still appropriate and willing to serve?
- Asset ownership and titling: Do deeds, account registrations, and jointly held assets work consistently with the plan?
- Digital assets and records: Can the right person locate important documents, account information, and digital property when needed?
- Business interests: Does the plan align with any buy-sell agreement, operating agreement, succession plan, or co-owner arrangement?
Estate-Plan Review Checklist
Before your next meeting, gather your current estate-planning documents and make a short list of changes since they were signed. Include changes in family members, residences, assets, debts, insurance, retirement accounts, business ownership, charitable goals, and the people you have named to act for you. Bring your original documents to your consultation with your estate planning attorney so that they can understand your prior plan and where you want it to go.
It is also helpful to confirm that your fiduciaries know where the originals are stored. Keep documents secure, but make sure the people who may need them can locate them when the time comes.
Frequently Asked Questions
Do I need to update my will every year?
Usually not. An annual check-in can be useful, but a full update is generally most important when circumstances, assets, family relationships, or the law have materially changed. In the absence of major changes, a review every three to five years is a practical starting point.
Is updating my will enough?
Not always. A will does not control every asset. Retirement accounts, life insurance, accounts with beneficiary designations, jointly owned property, and certain transfer-on-death arrangements may pass outside the will. Review the complete plan rather than updating one document in isolation.
Can I make changes to my estate plan myself?
Informal changes can create uncertainty or conflict, and the requirements for valid changes vary by state and document type. Before altering, crossing out, or adding language to a signed estate-planning document, seek legal guidance about the appropriate method.
What happens if I never update my estate plan?
Your estate plan may no longer reflect your current wishes. An outdated fiduciary appointment, a former beneficiary, an unaddressed new asset, or a change in family circumstances can complicate administration and create unintended results.
The Bottom Line
Estate planning works best as an ongoing process—not a document you sign once and forget. Put a reminder on your calendar to review your plan every three to five years, and schedule a review sooner after a major life event or meaningful financial change.
A current estate plan can provide clarity for you and reduce uncertainty for the people you care about. If your life has changed since you last signed your documents, now is a good time to have them reviewed.
At Minter & Pollak, we help individuals and families throughout Wichita and Kansas update their estate plans based on their specific circumstances and goals.
Call our office today at 316-265-0797 or click here to schedule a free consultation to create a plan that protects your family’s future.
Photo by Scott Graham on Unsplash
Disclaimer: The information on this website and in its blog posts is provided for general informational purposes only. It is not legal advice and should not be relied upon as a substitute for advice from a qualified lawyer or other professional regarding your particular circumstances.
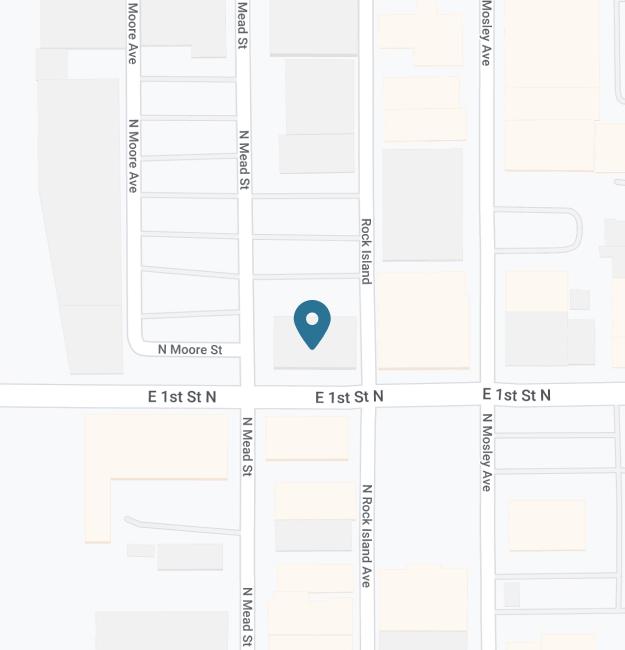
Address
Our offices are located in the heart of Wichita's Old Town at the corner of First and Mead with plenty of free parking available.